
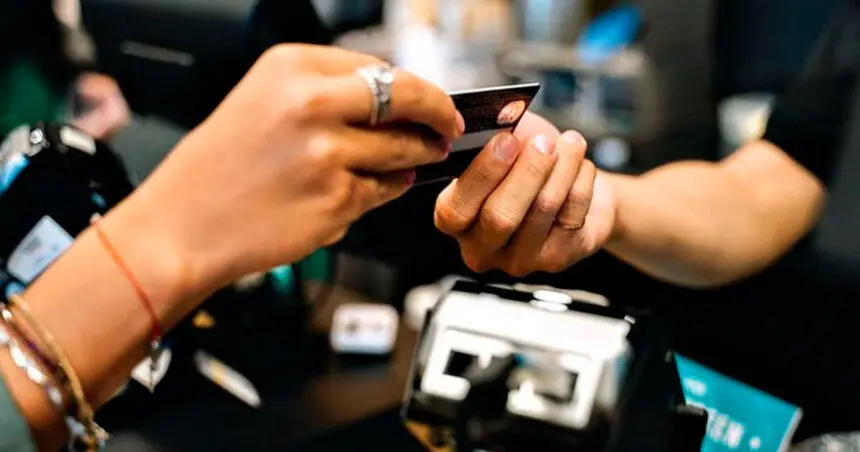
A LOOMING ban on card payment surcharges could have implications far beyond the cafe counter, with local trades, service providers and even body corporate managers considering how to absorb the cost of electronic payments.
From October 1, businesses will no longer be able to impose a separate surcharge on EFTPOS, Visa, Mastercard, American Express, JCB and UnionPay transactions.
The change applies wherever card payments are accepted, from shop counters and restaurants to mobile EFTPOS machines in work vans and on-site service calls.
While early discussion has focused on hospitality, tourism and retail businesses, which process high volumes of card transactions, local business owners say the impact could be just as significant for operators issuing larger invoices.
One local electrical company said customers increasingly chose to pay substantial invoices by credit card to collect rewards points, leaving the business to cover potentially sizeable processing fees.
“We have no choice but to add it,” the business owner said.
“Customers want to get credit card points, meaning I will have to pay $200 in some cases for a customer to pay via card and get the points.”
For trades and service businesses processing invoices worth thousands of dollars, the fee attached to a single card transaction can be substantial.
The Reserve Bank of Australia’s March 2026 Conclusions Paper noted interchange caps were based on a “user pays” philosophy, meaning merchants should not have to subsidise benefits such as rewards points offered by banks to encourage customers to use higher-cost cards.
However, not every business sees the change as a major disruption.
Another local tradie said they had never passed card processing fees on to customers, instead treating them as part of the ordinary cost of doing business.
That difference in approach is likely to shape how individual businesses respond to the surcharge ban.
Some may absorb the cost with little change to their existing pricing, while others may review prices across their business to recover fees that were previously charged separately at the point of payment.
That could have a broader cost-of-living effect.
While customers may no longer see an additional charge when tapping their card, merchant costs built into general prices could potentially be shared by all customers, including those paying with cash or direct transfer.
The approach will not suit every business, but it is one possible flow-on effect as operators adjust.
There are also signs some organisations may simply reduce card payment options.
It has been reported that at least one body corporate manager has advised owners it will remove credit card payment options rather than have merchant fees paid from shared body corporate funds.
It is unclear how widespread that response may be, or whether it reflects a broader industry position.
The reform is expected to lower interchange fee caps from 0.8 per cent to 0.3 per cent, reducing some costs for merchants.
But businesses say the key question will be what they are ultimately charged by their own payment provider.
For small businesses already managing higher insurance, wages, superannuation, compliance and operating costs, the change will mean another review of systems, invoicing arrangements and pricing.
The surcharge may disappear from the tap, but the cost of accepting card payments will remain.