
A higher income can create more choice, more comfort and greater financial security.
But if extra income is absorbed into higher spending and larger commitments, it can be difficult to see any real improvement in your financial position.
Financial wellbeing is about how effectively your income supports your life, strengthens your resilience and helps you make progress towards the things that are important to you.
INCOME IS JUST A STARTING POINT
Two households can earn the same amount and experience their finances very differently. One may have cash reserves, manageable debt and money regularly directed towards future goals. Another may have a similar income but still find themselves surviving from one pay cycle to the next.
The difference is what happens after the income arrives.
As income increases, some of that additional capacity should ideally strengthen your financial position. This could include building an emergency fund, reducing consumer debt, setting money aside for irregular expenses, making additional mortgage repayments, increasing super contributions or investing consistently.
GIVE YOUR INCOME A JOB
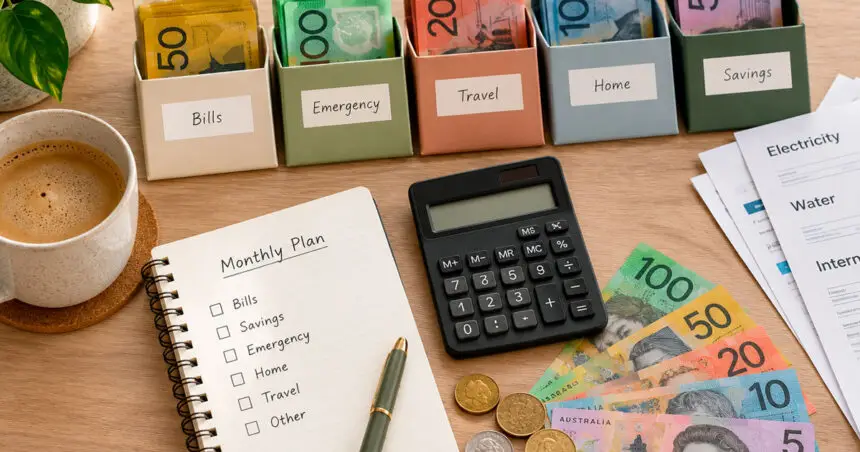
A practical approach is to allocate your income across several clear purposes rather than allowing everything to flow through a single pool of money.
Start with your everyday living costs, include housing, groceries, utilities, transport and other regular commitments. Then allocate money towards future expenses, such as annual bills, car costs, holidays, school expenses or home maintenance.
Next, direct some income towards your financial safety net, through an emergency fund or additional debt repayments. Another portion can go towards long-term wealth, including investing, additional super contributions or paying down your mortgage faster.
Finally, deliberately allocate some income to lifestyle and enjoyment. Spending on the things you value can sit comfortably alongside saving for the future when you plan effectively.
MEASURE PROGRESS IN A NEW WAY
Income is an easy number to focus on, but it is only one measure of financial progress. A more useful assessment is whether your income is creating more options in your life.
Could you manage an unexpected expense without relying on a credit card? Are your debts reducing over time? Are you building savings and investing for the future?
These questions and others will give you a much clearer picture of your real financial wellbeing, rather than simply focusing on your income alone.
Income is important; just make sure that, as your income grows, your financial wellbeing grows with it.